

FaithFi: Faith & Finance
FaithFi: Faith & Finance
- 3.6
- 85.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
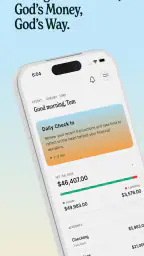
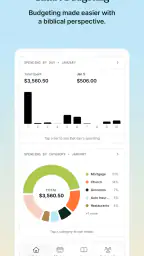
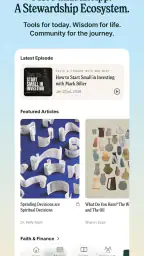
FaithFi: Faith & Finance Pros and Cons
Pros
- Combines biblical principles with practical budgeting tools.
- Helps connect financial goals with personal faith and values.
- Simple interface makes tracking spending approachable for beginners.
- Encourages intentional saving and debt reduction habits.
- Offers reflection prompts that can support mindful money decisions.
Cons
- Some features may require a paid subscription or in-app purchase.
- Religious guidance may not suit users seeking a secular finance app.
- Budgeting tools may feel limited for advanced financial planning.
- Requires regular manual input if bank syncing is unavailable.
- Financial advice should complement, not replace, professional guidance.
 Analysis by All-app
Managing money is difficult enough without feeling that every budgeting decision is separate from personal values. FaithFi: Faith & Finance approaches the problem from a Christian perspective, and that makes it more focused than a typical finance app. I found it most useful as a companion for thinking through spending, saving, giving, and financial priorities rather than as a replacement for a bank app or a full accounting system.
The app is free to install, with optional in-app purchases ranging from $3.99 to $11.99 per item. It is made by FaithFi: Faith & Finance, carries an Everyone content rating, and supports Android devices running version 7.0 or later. The current version is 5.1.3. Its audience is clearly people who want faith and everyday money decisions to sit in the same conversation, not users looking only for charts, stock prices, or automated bill negotiation.
How FaithFi fits into everyday money management
When I opened FaithFi: Faith & Finance, the main appeal was its point of view. Many finance tools treat money as a purely numerical problem: track the transaction, reduce the category, and repeat. That can be useful, but it does not answer the personal questions behind the numbers. FaithFi is aimed at users who also want to reflect on generosity, stewardship, contentment, and responsible choices.
That difference matters in practice. A conventional budgeting app may tell me that I spent too much on dining out. FaithFi is better suited to helping me ask why that spending happened, whether it matches my priorities, and what I want my money to support next month. I would not choose it simply because I need a faster way to check my bank balance. I would choose it because I want a values-based framework around financial habits.
The app has reached over ten thousand installs and holds an average rating of 3.6 from around 160 ratings, with roughly 85 written reviews. That reception suggests a product with a defined audience but not universal appeal. My impression is similar: the faith-centered approach is a genuine strength for the right person, while it will feel unnecessary or restrictive to someone seeking a neutral personal-finance dashboard.
What I would use it for first
I would begin with one specific goal rather than trying to reorganize every part of my financial life at once. For example, I might use it during a monthly review to look at whether my spending reflects my priorities, then write down one adjustment for the following month. That small workflow is more realistic than expecting an app to solve debt, irregular income, and household disagreements in a single sitting.
A useful everyday scenario would be a couple reviewing their budget after payday. Instead of discussing only which category went over target, they could use the app as a prompt to talk about giving, saving for a shared purpose, and distinguishing needs from impulse purchases. The value is not merely recording a transaction; it is making the conversation less reactive and more intentional.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
For an individual, the same approach can work after receiving an unexpected expense. I would open the app before immediately cutting a random category, identify what matters most, and decide whether the expense calls for a temporary change or a permanent habit adjustment. That makes the tool more reflective than a spreadsheet, although a spreadsheet remains better when I need detailed formulas and complete control.
Speed during ordinary use
FaithFi is not the kind of finance app I would judge by how quickly it displays a stock quote or refreshes a bank feed. Its usefulness depends more on whether I can move from a money concern to a clear decision without feeling overwhelmed. In ordinary sessions, I would expect the experience to feel manageable when I focus on one task at a time: reviewing a habit, considering a goal, or preparing for a financial conversation.
The relatively modest install footprint also makes it seem approachable for people who do not want a large, demanding finance suite. Still, install size alone does not prove that every screen will be fast on every phone. Older hardware, limited free storage, or a crowded device can affect any app. I would keep expectations practical rather than assuming that the minimum Android requirement guarantees identical performance across all supported devices.
One tip I found important is to avoid opening the app without a question in mind. A vague session can turn into passive reading or unfocused browsing. Before launching it, I would decide whether I am checking spending behavior, planning a conversation, or thinking about a specific goal. That simple habit makes a values-based tool feel more actionable and reduces the temptation to treat it as another app to scroll through.
What happens during heavier use
The more demanding moments are likely to come from the user’s workflow rather than from graphics or entertainment-style processing. A long financial review can involve several decisions at once: looking at recent spending, comparing it with intentions, considering household priorities, and deciding what to change. That mental load can make the app feel slower even when the phone itself is responding normally.
I would therefore use it in short sessions, especially on a phone with limited memory or an older processor. Closing unrelated apps before a serious review may help keep the device responsive, but I would not present that as a guaranteed fix. The practical lesson is to separate reflection from data entry. I would first gather the information I need, then use FaithFi for the decision-making part instead of repeatedly switching between many apps.
Another non-obvious trade-off is that a faith-centered finance workflow may take longer than a purely mechanical one. If my only aim is to categorize a purchase, a conventional tracker can be quicker. FaithFi earns its place when I am willing to pause and connect that purchase with a broader principle. The extra reflection is a benefit for some users and friction for others.
For heavy household use, I would also establish a routine rather than relying on spontaneous checks. A weekly review can be easier to sustain than a long session at the end of the month. If several people share financial responsibilities, agreeing on the purpose of the review beforehand can prevent the app from becoming a source of blame. The tool can support a conversation, but it cannot replace agreement between the people involved.
Stability and recovering from interruptions
Finance apps need to inspire confidence because users may be thinking about sensitive decisions while using them. My standard for FaithFi would be straightforward: the app should let me return to my financial reflection without losing the thread after a phone call, a notification, or a brief interruption. I would still save important notes or decisions elsewhere if they are essential, because no mobile app should be the only place where a major financial plan exists.
Recovery is especially important when I am using an older Android phone. If the operating system closes an app in the background, I would want to know exactly where I left off, but behavior can vary with device memory and system settings. The safest workflow is to complete one small task before switching away, then reopen the app and confirm that the result or note was retained.
I would also avoid treating FaithFi as the authoritative record of my bank account unless its particular setup matches my needs. A banking app, statement, or separate backup should remain the reference for actual balances and transactions. FaithFi is more valuable as a guide for habits and values. Keeping those roles separate makes recovery easier: if the app needs to be reopened or reinstalled, the underlying financial records are still available elsewhere.
The rating of 3.6 is worth considering without overinterpreting it. It indicates a mixed overall experience among users, but ratings alone do not explain whether dissatisfaction came from performance, expectations, content, or device compatibility. I would read the written feedback before making it the center of my financial routine, particularly if I depend on the app every day.
Device limits and practical compatibility
Support for Android 7.0 or later gives FaithFi a broad potential device range, including phones that are no longer new. That is helpful for users who do not upgrade frequently. At the same time, an older operating system can come with slower hardware, less available memory, and different background-management behavior. The app may install successfully while still feeling less comfortable on a low-end phone than on a newer one.
I would leave some free storage available and keep the operating system in its normal working condition before beginning a serious budgeting routine. I would also avoid using a nearly full device for important financial administration. These are not FaithFi-specific guarantees, but they are sensible precautions for any app that I expect to open reliably when I need it.
Resource demands matter less here than they would in a game, yet a finance app should not become a burden. If I notice slow transitions, repeated reloads, or difficulty returning after interruptions, I would reduce the number of open apps and test the experience again. If the problem continued, I would use a simpler notes-based system or a spreadsheet for the core record and keep FaithFi for reflection.
Privacy and trust also influence my device choice. I would use a personal phone protected by a screen lock rather than a shared tablet or an unsecured spare device. I would be cautious about entering more personal information than the app genuinely requires for my chosen workflow. A values-based finance tool can encourage good decisions, but good device habits remain my responsibility.
Where it beats ordinary alternatives
Compared with a bank app, FaithFi offers a different kind of usefulness. A bank app is usually the better place to confirm balances, move money, and inspect official transaction records. FaithFi is better when I want to step back from the account activity and think about what those numbers mean in the context of my beliefs and priorities.
Compared with a spreadsheet, the app should be easier for a person who wants guidance and a mobile-first routine rather than formulas and custom categories. A spreadsheet wins when I need unusual calculations, detailed forecasting, or a structure designed entirely around my household. FaithFi wins when I need a repeatable prompt to connect financial behavior with personal convictions.
Compared with a general budgeting app, the key distinction is not necessarily more financial machinery. It is the Christian framing. That can make the experience feel more relevant and encouraging for a Christian user, but it also means the app is not the ideal neutral tool for a mixed-belief household unless everyone is comfortable with that perspective.
I would not recommend making it the only tool for a complex financial situation involving multiple accounts, investments, business expenses, or detailed debt schedules. A dedicated accounting or budgeting system may be more precise there. FaithFi can still serve as a companion for goals and reflection, but expecting it to replace specialized software would create unnecessary frustration.
Who should try it, and who should skip it
I think FaithFi is a good fit for someone who wants money management to include prayerful or faith-informed reflection, generosity, and stewardship. It may also help a beginner who feels that conventional budgeting is too cold or too focused on restriction. The app gives that person a reason to examine habits beyond simply chasing a lower spending total.
It may be particularly useful for a user beginning a new financial routine. I would suggest choosing one recurring review time, writing down a small number of priorities, and using the app to evaluate progress without turning every mistake into a moral judgment. That distinction matters: values can guide a budget, but shame rarely makes a budget sustainable.
I would skip it if I want a completely secular interface, advanced financial modeling, or a single source for every account and transaction. I would also look elsewhere if I dislike reflective prompts and want the shortest possible path from opening an app to seeing a balance. The free entry point makes trying it easy, but the optional purchases mean I would check what each paid item adds before spending money.
The Everyone rating makes it suitable for a broad audience from an age-classification perspective, but suitability is still personal. Parents introducing money concepts to a child should guide the discussion rather than assuming the app alone teaches financial judgment. For adults sharing finances, the most important question is whether both people actually welcome the faith-based approach.
My practical routine after testing it
If I kept FaithFi on my phone, I would use a three-step routine. First, I would review what happened without immediately criticizing myself. Second, I would identify the value or priority that should guide the next decision. Third, I would choose one concrete action, such as delaying a discretionary purchase, setting aside money for a goal, or discussing a giving plan with my household.
The strongest tip is to turn reflection into a calendar habit. Without a regular time, a finance app can become something I open only after a problem appears. A short weekly check is enough to notice patterns earlier, while a longer monthly session can handle broader planning. Keeping those sessions separate prevents every review from becoming an exhausting audit.
I would also pair the app with a secure external record for balances, account details, and important commitments. That division of labor is a strength, not a weakness: FaithFi can shape the questions I ask, while my bank, statements, or spreadsheet preserve the precise numbers. It is a safer and more flexible workflow than forcing one mobile app to do everything.
Final performance verdict
FaithFi: Faith & Finance feels most convincing when I treat it as a faith-centered companion for financial reflection rather than a complete replacement for banking or accounting software. Its likely performance demands are modest compared with graphically intensive apps, and the broad Android compatibility is encouraging for people using older phones. Even so, device age, available memory, and background behavior can affect how smoothly any finance routine feels.
My overall recommendation is conditional but positive. If you want Christian principles to shape how you think about spending, saving, and generosity, this free app is worth trying before committing to its optional purchases. If you need detailed automation, complex calculations, or strictly neutral budgeting, a conventional finance tool will probably serve you better.
The app’s real value is not speed alone. It is the pause between seeing a number and deciding what that number should mean. Used alongside reliable financial records and a realistic review routine, FaithFi can make money conversations more intentional. Used as the sole answer to complicated finances, it may feel limited. For the right user, that focused purpose is exactly what makes it useful.
Frequently Asked Questions
What is FaithFi: Faith & Finance, and who is it designed for?
FaithFi: Faith & Finance is a personal finance app designed to help users manage money while reflecting on Christian principles of stewardship. It combines budgeting and financial organization tools with Bible-based encouragement, devotional content, and practical guidance. It may be useful for individuals, couples, or families who want to approach spending, saving, giving, and debt management through a faith-centered perspective.
What financial features are available in FaithFi: Faith & Finance?
The app generally focuses on helping users build healthier financial habits through tools such as budgeting guidance, spending awareness, savings goals, debt-related education, and financial reflections. Depending on the current version and platform, some features may require an account or subscription. Before downloading, users should review the app’s latest listing to confirm whether bank connections, transaction tracking, or other advanced tools are supported.
Does FaithFi: Faith & Finance connect directly to my bank accounts?
Bank-account connectivity can vary according to the app version, region, and available integrations. Users should not assume that every bank or financial institution is supported. If account linking is offered, carefully review the permissions, privacy policy, security information, and third-party services involved before entering credentials. Those who prefer not to connect accounts may still benefit from educational content and manual financial planning features.
Is FaithFi: Faith & Finance free to download and use?
The application may be available to download at no initial cost, but certain lessons, courses, tools, or premium resources could be restricted behind in-app purchases or a subscription. Pricing, trial periods, and included features can change, so check the official Google Play or App Store listing before installing. Also verify renewal terms if you start a trial, particularly if automatic billing is enabled.
Is FaithFi: Faith & Finance suitable for professional financial advice?
FaithFi: Faith & Finance should be viewed as an educational and organizational resource rather than a replacement for a qualified financial adviser, tax professional, attorney, or credit counselor. Its faith-based guidance may help users reflect on financial decisions and develop practical habits, but personal circumstances differ considerably. For investments, taxes, bankruptcy, major debt, or other high-impact decisions, seek independent professional advice before acting.


